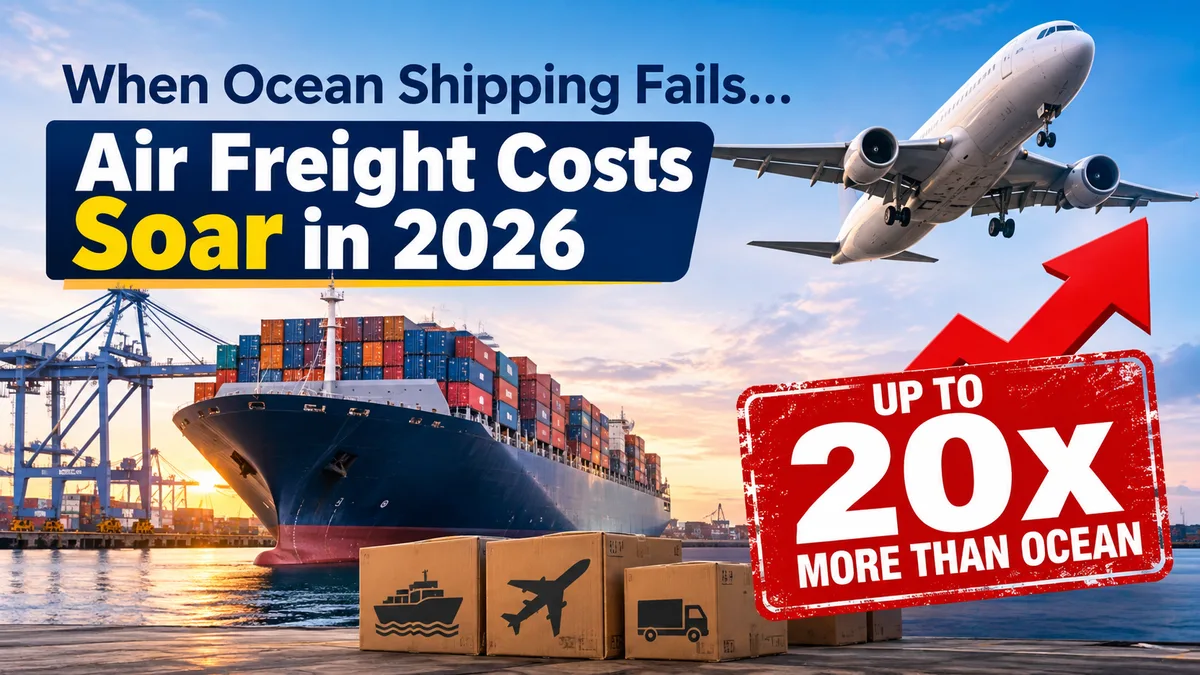
When ocean shipping fails, shippers reach for the phone and call their airfreight forwarder. But in 2026, that call is coming at an increasingly painful cost — and earnings disclosures from some of the world's best-known companies are now putting hard numbers on exactly how painful.
Recent financial reports from Rico Auto Industries, NETGEAR, and Logitech have all flagged emergency airfreight costs as a material factor squeezing profit margins this quarter. The pattern is consistent: an ocean supply problem — whether a missed sailing, port congestion, or unreliable scheduling — creates a production or delivery deadline that cannot be met by sea, forcing the shipper to fly the cargo at a cost that can be up to 20 times higher than the equivalent ocean rate.
The Numbers Behind the Pain
In Rico Auto Industries' case, the company was forced to increase production and supply customers by air simultaneously — while rebuilding its ocean pipeline and warehouse stocks. The cargo in question included new iron components, whose weight made flying them significantly more expensive than lighter goods. Management acknowledged that disruption was only part of the explanation; structural issues in the supply chain contributed equally to the cost.
The scale of this problem is confirmed by Xeneta's latest air freight market data, published November 11:
- Global air cargo spot rates stood at $3.11 per kilogram in October 2026 — up 29% year on year
- Spot rates increased 4% month on month in October
- The global dynamic load factor — measuring cargo volume, weight and available capacity — rose to 63%, up two percentage points
- Europe to North America spot rates hit $2.31 per kilogram, up 10% year on year, as carriers shifted to winter flight schedules and tightened capacity
Ocean Reliability Is the Root Cause
The airfreight cost surge is inseparable from the state of ocean shipping. According to Xeneta, ocean schedule reliability from the Far East to North Europe was still only around 10% in October 2026 — meaning nine out of ten shipments are arriving off-schedule. With scheduled container shipping capacity crossing the Red Sea now at approximately half its pre-crisis level, and the Strait of Hormuz still severely disrupted after more than eight months of conflict, shippers have limited confidence that ocean cargo will arrive when promised.
The result is a structural — not temporary — shift in how freight capacity is being purchased. Xeneta's analysis of new air cargo contracts starting from Q3 2026 found that 60% were for three months or less, compared with just 25% in Q3 2025. Three-month agreements alone accounted for 42% of new contracts, up from 16% a year earlier. Meanwhile, the share of 12-month contracts fell from 40% to 25%, and contracts of more than 12 months have effectively disappeared at just 3% of new deals.
Niall van de Wouw, Chief Airfreight Officer at Xeneta, described the market shift bluntly: "A one-year deal without any adjustment mechanism is becoming more the exception than the rule. If they do exist, not many will survive the upcoming 12 months."
Not a Full Modal Shift — But Costly for Those Caught Out
DSV, the world's largest freight forwarder, offered important context at the TIACA Air Cargo Forum in Miami earlier this month. Head of global airfreight Achim Martinka cautioned that ocean disruption is not triggering a large-scale switch to airfreight across the industry — the cost premium is simply too high for most shippers to absorb as a standing practice. Most companies have developed emergency airfreight plans since Covid but are not routinely shifting ocean volumes to air.
The issue, as Martinka and JTD Advisory founder David Kerr both noted, is timing. Shippers that wait too long before seeking an air alternative — hoping the ocean disruption resolves itself — find that by the time they book, available capacity has become prohibitively expensive. Kerr advises buyers to focus on securing capacity early and to scrutinize fuel surcharge terms alongside headline rates when evaluating airfreight options.
What to Expect in Q4 and 2027
Despite the cost pressure, Xeneta's data suggests the year-end surge in air cargo volumes that markets traditionally expect in Q4 is unlikely to materialize strongly in 2026. Many shippers are not negotiating new contracts in Q4 at all — instead waiting to run tender processes in Q1 or Q2 2027. Air cargo demand grew a steady 6% year on year in October, but the traditional late-year spike driven by holiday retail shipping is not showing up in the forward signals.
Looking further ahead, Xeneta's baseline forecast anticipates an overall decline in air freight rates in 2027 — particularly if Middle East disruptions ease and ocean capacity becomes more reliable. Global ocean spot rates are separately forecast to fall 30% in 2027 versus Q3 2026 levels, according to Xeneta, as fleet growth from the record 2024–2026 newbuild cycle outpaces demand.
For shippers and forwarders managing freight budgets into year-end and 2027 planning cycles, the message is clear: emergency airfreight is an expensive fix for a structural problem. Building contingency capacity agreements now — before the next disruption forces the issue — is the only way to manage the cost.
🔑 Key Takeaways — November 12, 2026
- Air cargo spot rates at $3.11/kg — up 29% year on year per Xeneta October data, published November 11, 2026.
- Rico Auto, NETGEAR, and Logitech all flagged emergency airfreight costs in recent earnings — putting real numbers on what supply chain disruption costs in practice.
- Ocean schedule reliability from Far East to North Europe: just 10% — nine out of ten shipments arriving off-schedule is driving the forced modal shift.
- 60% of new air cargo contracts are now 3 months or less — shippers avoiding long-term commitments due to market volatility and uncertainty.
- Flying cargo can cost up to 20x more than ocean — but waiting too long before booking makes it even more expensive as capacity tightens.
- No major year-end air cargo volume surge expected in Q4 2026 — Xeneta data shows traditional late-year spike signals are absent.
- Air freight rates forecast to decline in 2027 — if Middle East disruptions ease. Ocean spot rates also forecast down 30% from Q3 2026 peaks as new fleet capacity arrives.
Source date: November 11, 2026 | Published: November 12, 2026
Comments
No comments yet. Be the first to share your thoughts!