What Is Happening in Air Cargo Right Now?
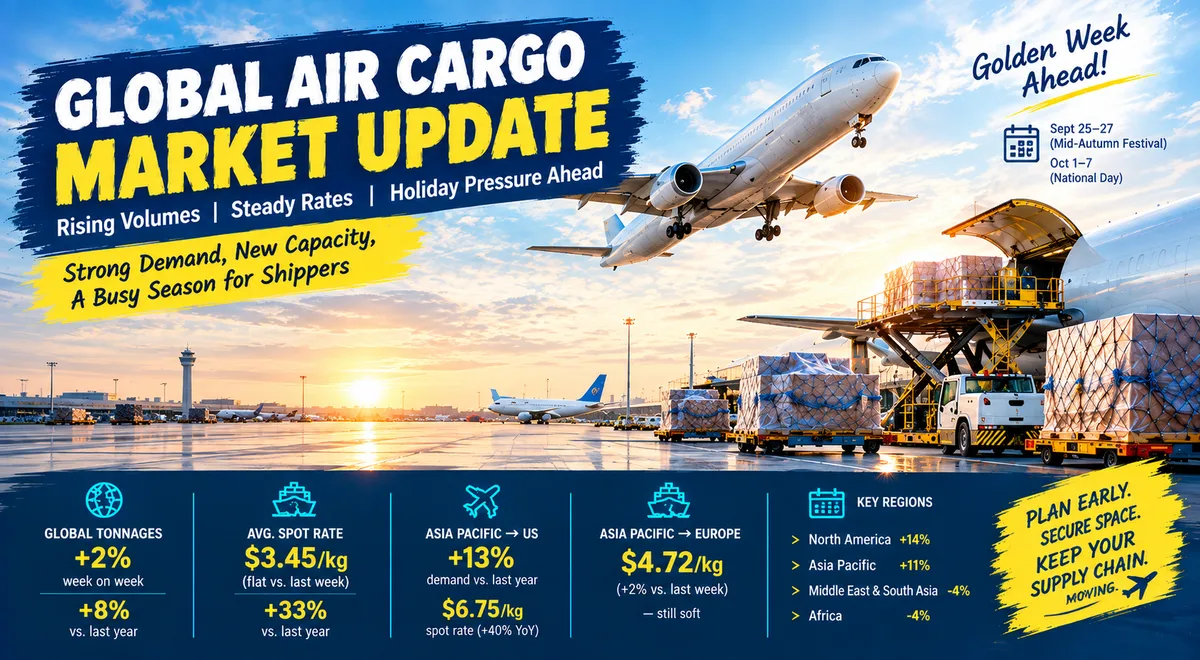
Global air cargo is bouncing back. According to the latest weekly data from WorldACD Market Data, worldwide tonnages rose 2% week on week in week 38 (September 14 to 20, 2026). This is the fourth week in a row of rising volumes.
The rebound follows the usual dip around Labor Day in the US and Canada on September 7. The numbers are also strong compared with last year. Tonnages, rates and capacity are all higher than this time in 2025, across every major region.
The Key Numbers
- Global tonnages: up 2% week on week and up 8% compared with the same week last year
- North America: volumes jumped 14% week on week, returning to their level from the previous few weeks
- Asia Pacific: volumes are 11% higher than last year, the biggest driver of yearly growth
- Middle East and South Asia: down 4% week on week
- Africa: also down 4% week on week
- Average worldwide spot rate: flat at $3.45 per kilo, but 33% higher than last year
- Average full-market rate (spot plus contract): broadly stable, but 24% higher than last year
In simple words: more cargo is flying, prices are not rising further this week, but they are still much higher than a year ago.
Why Are Shippers in a Hurry? China's Two Holidays
Two Chinese holiday periods are arriving very close to each other:
- Mid-Autumn Festival: September 25 to 27
- National Day Golden Week: October 1 to 7
Freight forwarders say this squeezes production, export handovers and freight planning into a very small window. When ocean freight schedules are missed, air freight often becomes the "pressure release" option. Urgent shipments, high-value goods and e-commerce cargo all compete for limited space before and just after Golden Week.
Forwarders report that general cargo demand from North China is rising because shippers want to push goods out before the holiday. From Southern China, demand on transpacific routes is also rising. E-commerce volumes, however, are still fairly soft.
Why Are Rates Not Jumping, Then?
Even with stronger demand, rates are holding steady. The reason is new charter capacity. Extra charter flights entering the market are absorbing the pressure that stronger cargo volumes would normally put on prices.
Worldwide capacity rose about 1% week on week. Freighter capacity grew almost 2%, while passenger capacity dipped slightly. Compared with last year, total international capacity is up 4%, and freighter capacity is up 5%.
Asia to the US: Strong Demand, High Prices
Demand from Asia Pacific to the US is 13% higher than last year. Some big increases by origin country:
- South Korea: up 54% year on year
- Japan: up 47%
- China: up 14%
- Indonesia: up 19%
- Thailand: up 12%
- Singapore: up 10%
The average spot rate from Asia Pacific to the US was stable at $6.75 per kilo, but that is around 40% higher than the same week last year. Singapore-origin rates are up 62% and Japan-origin rates are up 50% year on year.
Asia to Europe: A Softer Picture
Asia to Europe is a different story. Demand is still soft, and rates are relatively calm. The average spot rate from Asia Pacific to Europe rose 2% to $4.72 per kilo.
China and Hong Kong to Europe has been under pressure since the EU removed its "de minimis" exemption on low-value imports on July 1. After four weeks of slow recovery, volumes slipped back a little in week 38. Hong Kong to Europe was down 5% week on week and down 29% compared with last year. Mainland China to Europe is broadly stable, up 2% year on year.
What About the Gulf Region?
Capacity in and out of the Gulf area is still down almost 17% compared with the start of the regional conflict earlier this year. Traffic from the Middle East and South Asia region to the US fell 5% in week 38. That included drops from India (down 5%), Bangladesh (down 17%) and Sri Lanka (down 10%). Some Gulf markets remain volatile.
Not all regions are behind, though. Capacity to and from Europe is up 19% compared with the pre-conflict level.
What Does This Mean for You?
If you ship by air from China or the wider Asia Pacific region, the next two weeks are important. The rebound in volumes, plus the holiday rush, means space can tighten quickly around Golden Week even if rates look calm today.
- Exporters in China: expect a rush to fly goods out before October 1, then another wave of urgent cargo right after October 7.
- Importers in the US: demand from Asia is strong and rates are about 40% above last year. Do not assume space will be easy to find.
- Importers in Europe: demand from Asia is softer, so you may have more room to negotiate.
- Sellers of low-value e-commerce goods: the EU rule change is still affecting China and Hong Kong to Europe volumes.
- Anyone using Gulf routings: capacity is still limited, so build extra time into plans.
What Should Shippers and Forwarders Do Now? Step by Step
- Step 1: Check your cut-off dates. Ask your forwarder for the last booking and cargo acceptance dates before Golden Week (October 1 to 7).
- Step 2: Book space early. If you have urgent or high-value cargo, confirm your air space this week instead of waiting.
- Step 3: Separate urgent from non-urgent. Keep air freight for time-critical goods. Move less urgent shipments to ocean or plan them for after the holiday.
- Step 4: Ask for all-in quotes. Rates look steady, but ask for the full price including fuel and other charges so there are no surprises.
- Step 5: Plan for the restart. Forwarders expect competition for uplift immediately after Golden Week too. Talk to your forwarder about space for the week of October 8.
- Step 6: Watch the weekly data. WorldACD publishes new numbers every week. Check whether volumes and rates rise or fall after the holiday.
Key Takeaways
- Global air cargo tonnages rose 2% week on week in week 38 (September 14 to 20), the fourth weekly rise in a row.
- Volumes are 8% higher than last year, led by Asia Pacific (up 11%).
- Average worldwide spot rate is $3.45 per kilo, flat this week but up 33% year on year.
- China's Mid-Autumn Festival (September 25 to 27) and Golden Week (October 1 to 7) are pushing shippers to move cargo early.
- Asia Pacific to the US demand is up 13% year on year, with spot rates at $6.75 per kilo, about 40% higher than last year.
- Asia Pacific to Europe stays soft at $4.72 per kilo, and China and Hong Kong to Europe is still affected by the EU de minimis change.
- New charter capacity is keeping rates from jumping, but the holidays could lift the transpacific market in the coming days.
- Book early, confirm cut-off dates and plan for the post-holiday restart.
Air cargo is starting the last quarter of 2026 with strong momentum. Steady rates and extra charter flights are helping for now, but the holiday rush in China could change the mood quickly on transpacific routes. Shippers who plan early will have the advantage.
Comments
No comments yet. Be the first to share your thoughts!