What's Happening
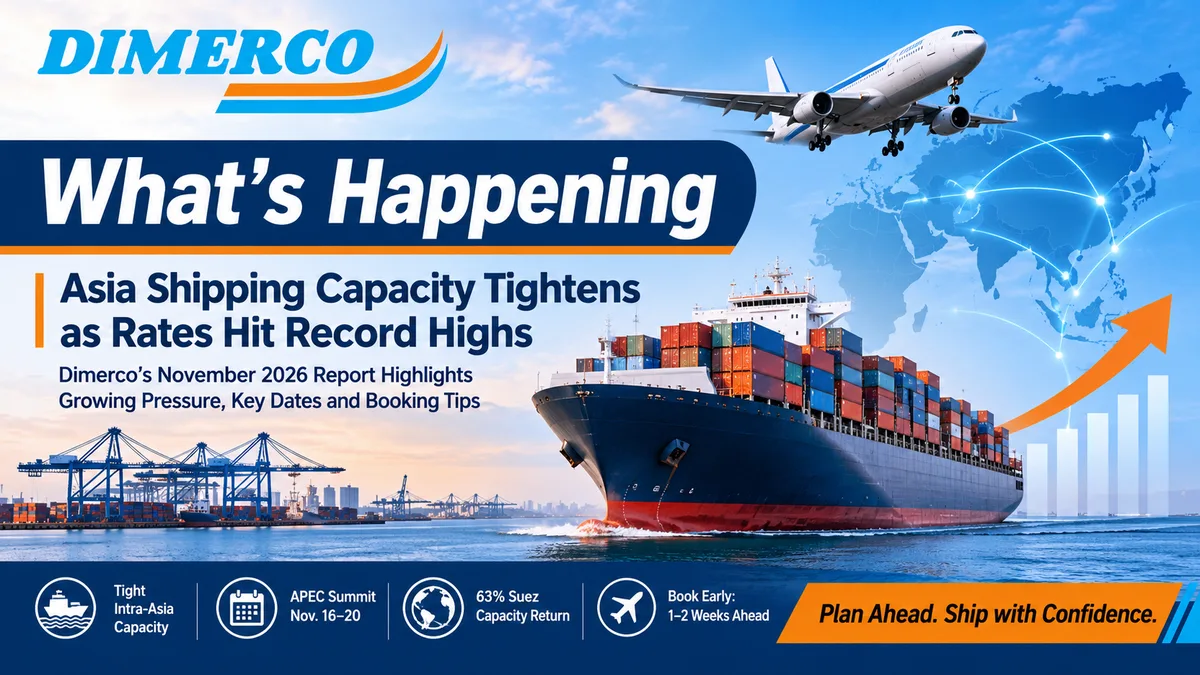
Shipping capacity within Asia is tightening significantly as ocean carriers redeploy vessels from regional short-sea services into more profitable long-haul trades, pushing intra-Asia ocean rates to record highs, according to Dimerco Express Group's November 2026 Asia Pacific Freight Report, published November 3, 2026.
"Everyone is watching Suez and the transpacific, but the tightest space in Asia right now is on the short-sea lanes," said Ted Chen, director of ocean freight, global sales and marketing at Dimerco Express Group. "When carriers pull feeder tonnage into deep-sea trades, a regional box can be harder to place than one bound for Europe — give intra-Asia bookings the same lead time as long-haul."
Where the Pressure Is Concentrated
Vessel redeployments, scarce feeder ships and cancelled sailings are restricting space on regional services from China. North China routes to Thailand, Vietnam, Indonesia and Malaysia remain tight, while South Korea also reports limited ocean space to Southeast Asia.
Regional capacity conditions vary considerably by origin:
- Thailand faces ocean backlogs
- Vietnam reports tight US-bound space, with cancelled sailings increasing the risk of cargo moving on a later vessel
- Singapore shows soft ocean capacity and stable rates, though vessel delays of three to five days from congestion and port omissions continue
- India reports soft capacity with stable rates across major lanes
Why Now? Strong Demand Meets Shrinking Regional Capacity
The squeeze is partly a function of genuinely strong underlying demand. The report cites a rise in the Global Manufacturing PMI to 53 in September, up from 52.3 in August — its highest level since February 2022 and a 14th consecutive month above the 50 threshold that separates expansion from contraction. Taiwan's manufacturing PMI reached 56.7 as export activity supported demand for freight capacity.
That demand strength is colliding with a capacity shift: carriers are pulling feeder vessels off shorter regional routes and deploying them on longer, more profitable deep-sea trades instead, leaving fewer ships available to serve intra-Asia lanes even as volumes on those routes hold up.
A Specific Date Shippers Should Watch: The APEC Summit
One operationally important detail in the report: the APEC Summit, scheduled for November 18-19, may halt cargo acceptance at Shenzhen terminals from November 16-20. Dimerco's advisory recommends shippers plan South China exports around this window specifically, since even a short terminal suspension at one of China's major export gateways can create a meaningful backlog once operations resume.
The Suez Return Is Changing the Long-Haul Picture Too
On the deep-sea side, the report estimates that approximately 63% of Far East-Europe capacity has now returned via the Suez Canal, with a full return expected by the first quarter of 2027. This fits a trend we've tracked closely in our own recent coverage of carriers gradually resuming Red Sea transits. The report also notes that eased Panama Canal draft limits are contributing to the broader long-haul capacity recovery.
Carriers lifted Asia-North Europe rates by 6% week-over-week through general rate increases, following a 12-week decline — but the report cautions that continued returning Suez capacity could put renewed downward pressure on pricing as more ships take the shorter route.
China-Europe: A Softer Lane, With One Firm Exception
China-Europe trade is staying comparatively soft, with new EU e-commerce handling fees taking effect from November keeping platforms cautious about shipment volumes. The UK stands out as the firmest lane within this broader softness, though Dimerco notes that Christmas stocking demand and rising fuel costs could still lift rates on quieter European lanes later in the month.
Air Cargo: AI Chips and Christmas Demand Keep Routes Tight
The air freight picture shows a similar story of concentrated pressure in specific corridors. Taiwan-US air capacity remains extremely tight as AI chip and server exports overlap directly with Black Friday and Christmas retail demand. Vietnam's US-bound air lanes and intra-Asia services from Kuala Lumpur and Penang are at backlog levels.
This connects directly to the broader AI infrastructure logistics trend we've covered extensively this year — semiconductor and data-centre component shipments competing for the same limited capacity as peak-season retail goods.
China-US airfreight rates, by contrast, are expected to ease from their recent peak as e-commerce platforms control volumes, with more relief reaching New York and Chicago than Los Angeles. Winter flight schedules are reducing cargo space available on passenger aircraft, even as AI server racks, electronics and Christmas replenishment continue supporting demand. "The U.S. rally has peaked, but space isn't opening up," said Kathy Liu, VP of global sales and marketing at Dimerco Express Group.
In North America, Asia-bound airfreight is also facing backlogs at Los Angeles, Chicago and Toronto.
Dimerco's Specific Booking Recommendations
The report includes concrete lead-time guidance for shippers navigating these conditions:
- Taiwan-US airfreight: book one to two weeks ahead
- Thailand ocean exports: book two to three weeks ahead
- Constrained intra-Asia ocean shipments generally: apply the same planning lead time used for long-haul cargo
Dimerco also advises building in additional transit time buffer around weather disruptions and the potential APEC-related Shenzhen cargo acceptance restrictions noted above.
What the Report Expects Heading Into Year-End
Dimerco's outlook for the remainder of the year is that rates will "settle high rather than drop," with Christmas stocking demand and fuel costs capable of lifting even quieter European lanes that might otherwise see softer pricing.
What This Means for Shippers and Freight Forwarders
- Treat intra-Asia bookings with the same lead time as long-haul shipments. As Dimerco's own director explicitly recommends, the assumption that regional Asian routes are easier to book than deep-sea trades no longer holds.
- Mark November 16-20 on your calendar if you export from South China. With the APEC Summit potentially halting Shenzhen terminal cargo acceptance during this window, plan shipment timing to avoid getting caught in a sudden backlog.
- Follow Dimerco's specific lead-time guidance where applicable. Book Taiwan-US airfreight 1-2 weeks ahead and Thailand ocean exports 2-3 weeks ahead — concrete numbers worth building directly into your planning calendar.
- Watch the Suez return for long-haul rate signals. With 63% of Far East-Europe capacity already back via Suez and full restoration expected by Q1 2027, anticipate renewed downward pricing pressure even after this month's rate increase.
- China-Europe shippers should watch new EU e-commerce handling fees closely. With these fees already making platforms cautious about volumes from November, factor this into demand and capacity expectations on this specific lane.
- Don't bank on rates falling into year-end. With Dimerco explicitly forecasting rates will "settle high rather than drop," plan budgets around sustained elevated costs through December.
Key Takeaways
- Intra-Asia ocean rates out of China have reached record highs as carriers redeploy feeder vessels into long-haul trades, per Dimerco's November 2026 Asia Pacific Freight Report.
- Thailand, Vietnam, Indonesia, Malaysia and South Korea all report tight or backlogged regional capacity; Singapore and India show softer conditions.
- The APEC Summit (November 18-19) may halt Shenzhen terminal cargo acceptance from November 16-20 — a key date for South China exporters.
- Global Manufacturing PMI rose to 53 in September, its highest since February 2022; Taiwan's PMI hit 56.7.
- Roughly 63% of Far East-Europe capacity has returned via Suez, with full restoration expected Q1 2027; eased Panama draft limits are also aiding long-haul recovery.
- China-Europe trade stays soft amid new EU e-commerce handling fees, with the UK the firmest lane.
- Taiwan-US air capacity remains extremely tight as AI chip/server exports overlap Black Friday/Christmas demand.
- Dimerco recommends booking Taiwan-US air 1-2 weeks ahead and Thailand ocean exports 2-3 weeks ahead.
- Dimerco expects rates to "settle high rather than drop" through year-end.
Comments
No comments yet. Be the first to share your thoughts!