What Happened to Rates This Week?
Container spot rates from Asia fell this week. According to The Loadstar's report on October 9, 2026, China's Golden Week holiday appears to have marked the end of the long transpacific peak season.
Here are the main numbers:
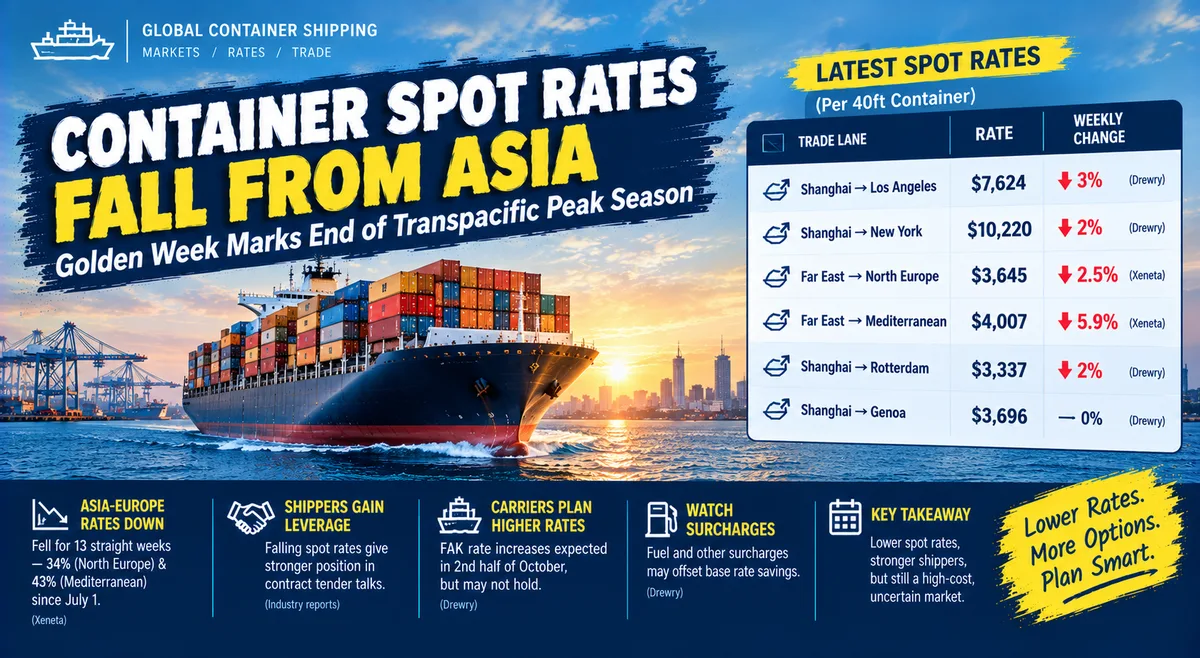
- Shanghai to Los Angeles: down 3% week on week to $7,624 per 40ft container (Drewry World Container Index).
- Shanghai to New York: down 2% to $10,220 per 40ft (Drewry).
- Far East to North Europe: down 2.5% to $3,645 per 40ft (Xeneta XSI).
- Far East to Mediterranean: down 5.9% to $4,007 per 40ft (Xeneta XSI).
- Shanghai to Rotterdam: down 2% to $3,337 per 40ft, and Shanghai to Genoa flat at $3,696 (Drewry).
These figures come from Drewry and Xeneta. They are different indices from the ones we quoted in our September 25 report, so the numbers should not be compared directly.
How Long Has the Europe Decline Lasted?
Spot rates on Asia-Europe routes have now fallen for the 13th week in a row. Xeneta's chief analyst, Peter Sand, said rates on these routes have dropped sharply since the July peak that followed the Hormuz crisis. The Mediterranean is down 43% since July 1, and North Europe is down 34%.
Sand also said demand has been very strong all year, especially into Europe, but it could not keep growing at double-digit rates forever. As demand eases from a very high level, the fight for capacity eases too. He added that the pace of the decline has slowed, but rates are still high and the trend is down, so "we are not at the floor yet."
Why Is This Good News for Shippers?
Contract season is starting. European shippers are now running tenders, and falling spot rates give them a stronger position, because contract bids are often compared against the short-term market. According to Sand, even freight forwarders are now getting better deals from carriers in long-term contract talks.
Chantal McRoberts, head of advisory at Drewry Supply Chain Advisors, spoke on a Journal of Commerce webinar on October 8. She said early signs from shippers who have opened tenders suggest rates could soften further, and some are seeing better rates than at the same time last year.
What Are Carriers Planning?
Carriers are not accepting the decline quietly. According to the report, the next two to three weeks will likely decide the pricing path for the rest of the year, and carriers will try to push through higher FAK (freight all kinds) rates in the second half of October.
Drewry said it is uncertain whether these increases will stick. Its view is that the faster-than-expected return of carriers to the Suez route is the biggest threat to their efforts to support rates. As we reported in August, major carriers have been returning to Suez, and more capacity on the shorter route puts more pressure on prices.
Watch the Surcharges
McRoberts gave an important warning. Price increases may come through surcharges rather than base rates. She said surcharges are causing the most concern right now, with inflated fuel charges and some high pre-peak-season surcharges appearing. Her advice was that shippers should put guardrails around contract rates, and think carefully about whether it is the right time to go to bid or better to extend an existing contract.
What Does This Mean for You?
- Europe-bound shippers have more leverage than at any point this year. Spot rates have fallen for 13 weeks, which helps in tender talks.
- US-bound shippers face a quieter market. The transpacific peak is fading, but carriers want to raise rates again in late October, so prices may not keep falling.
- The total cost is not the base rate alone. Fuel and other surcharges can cancel out savings, so compare all-in costs.
- The timing question is real. Rates are still high and not at the floor, so waiting a little may help some shippers, while others may prefer certainty.
What Should Shippers and Forwarders Do Now?
- Step 1: List all your carrier contracts that end in the next 90 days and note which lanes they cover.
- Step 2: Ask every carrier for an all-in quote, including fuel, peak-season and other surcharges, not only the base rate.
- Step 3: Use current spot rates as a benchmark in your negotiation, and ask for lower base rates on Asia-Europe lanes.
- Step 4: Put clear limits on surcharges in the contract, so rate savings are not lost later through added fees.
- Step 5: Decide whether to bid now or extend your current contract, and compare both options before the end of October.
- Step 6: Watch the carrier rate-increase announcements in the second half of October and check whether they actually hold.
Key Takeaways
- Golden Week appears to have ended the long transpacific peak season, and spot rates from Asia fell this week.
- Drewry: Shanghai-Los Angeles down 3% to $7,624 per 40ft; Shanghai-New York down 2% to $10,220.
- Xeneta: Far East-North Europe down 2.5% to $3,645; Far East-Mediterranean down 5.9% to $4,007.
- Asia-Europe spot rates have fallen for 13 straight weeks, down 34% (North Europe) and 43% (Mediterranean) since July 1.
- Falling rates strengthen shippers' hands in contract tenders.
- Carriers plan higher FAK rates in the second half of October, but a faster return to Suez could stop them.
- Drewry warns that price increases may come through surcharges, so shippers should set guardrails in contracts.
- Compare all-in costs, not only base rates, before you sign or extend.
Comments
No comments yet. Be the first to share your thoughts!